For almost six years, one of the best-known names in American hydroponics lived with an odd rule written into its loan papers. Hydrofarm, a Nasdaq-listed maker and distributor of grow lights, plant nutrients and growing media, believed that most of the equipment it sold ended up in cannabis grow rooms. Yet its lenders barred it from selling straight to a licensed cannabis grower. That one clause explains a great deal about why banks won’t work with cannabis, and about how far the problem reaches beyond the dispensary counter.
The rule is now gone. On November 3, 2026, Hydrofarm Holdings Group announced that it had eliminated a $109 million term loan and become debt-free, following a recapitalization that closed on October 27. Chairman and CEO Bill Toler singled out one consequence: the company can now sell its cultivation products directly to commercial cannabis growers, which he described as “removing a long-standing market access barrier.” The company’s own legal notes in the same release link that opportunity to the elimination of restrictions under the term loan.
In written answers to questions from The Cannex, including follow-up questions, Eric Ceresnie, Hydrofarm’s senior vice president of corporate development and international markets, described how the restriction worked in practice, which brands will lead the new direct channel, and how the company intends to keep its long-standing partners, the independent hydroponic stores, on side.
Key Takeaways
Banks and other lenders keep their distance from cannabis because marijuana is still illegal under US federal law outside a narrow medical carve-out, and money that flows from it can expose a financial institution to anti-money-laundering rules, extra reporting duties and regulatory risk. Those concerns do not stop at plant-touching businesses such as growers and dispensaries. Hydrofarm’s case shows how they travel down the supply chain through loan agreements: its 2020 IPO prospectus stated that its term loan prohibited its operating subsidiaries from selling directly to cannabis growers or to retailers serving only the cannabis industry, and later filings kept a similar ban. Growers bought through wholesale accounts instead, mostly independent hydroponic retailers and commercial resellers; Ceresnie told The Cannex that this network now numbers about 1,000 accounts and that the extra layer “created friction in the sales and service process.” The restriction ended when the $109 million loan, which cost about $12 million a year to service, was swapped for preferred stock and warrants given to the lenders, alongside an $8.3 million share sale. According to Ceresnie, commercial cannabis already accounts for about a third of Hydrofarm’s business, the company’s technical sales team advised commercial growers for years without being able to invoice them, and the new direct channel targets large-scale cultivators rather than the customers of hydroponic shops; outside the United States, he said, German cannabis social clubs can also open direct accounts. A federal watchdog report from August 2026 confirms that cannabis businesses and their suppliers still face account closures, high fees and expensive loans. Moving state-licensed medical marijuana to Schedule III in April 2026 did not create a banking safe harbor, recreational marijuana remains in Schedule I, and the SAFE Banking Act, reintroduced in June 2026, has not moved past the committee stage. Hydrofarm did not answer our question about other financial barriers such as banking, payments and insurance, and its announcement and comments describe plans, not evidence of new sales.
Why Banks Won’t Work With Cannabis: The Short Version
The core problem is simple to state. Most US states allow cannabis in some form, but the federal Controlled Substances Act still treats most marijuana as illegal. Banks, credit unions and large lenders are licensed, insured and examined by federal agencies, so they answer to federal law first. To a federal regulator, money earned from selling a federally illegal product can look like the proceeds of a crime, and handling such money is the territory of money-laundering law.
Washington has never fully closed this gap; it has only managed it. In February 2014 the Financial Crimes Enforcement Network, the Treasury agency that polices financial crime, issued guidance on how banks can serve marijuana-related businesses while meeting their duties under the Bank Secrecy Act. The guidance did not make cannabis banking legal. It told institutions how to do it without hiding anything: know the customer in detail, check the state license, and file suspicious activity reports on the account, using one of three labels depending on what the bank sees.
Think of it as a toll road where every driver with a certain sticker must be written up by the toll operator, every time, with no promise that the police will not stop the operator one day. Some operators decide the paperwork and the risk are worth the fees. Many decide they are not.
The Clause in Hydrofarm’s Loan Agreement
Hydrofarm never grew or sold cannabis. In industry language it is an ancillary business: it sells the lights, fans, pumps, nutrients and soils that growers use, and many of its customers grow tomatoes, herbs or flowers. That distinction did not satisfy its lenders.
When the company filed its registration statement for the initial public offering in November 2020, it spelled out the terms. The term loan agreement then in place prohibited the subsidiaries that held the debt from selling products directly to cannabis growers or cultivators, or to sellers and retailers that served only the cannabis industry. A separate revolving credit line went further and banned sales to the cannabis industry outright. A breach would count as a default, which would let the lenders demand immediate repayment.
The same prospectus made the commercial reality plain. The company said it believed a majority of the controlled environment agriculture equipment and supplies it sold were ultimately bought by cannabis industry participants, “though we do not sell to participants in the cannabis industry directly.” It also warned investors that the clause could make it more selective than competitors about who it sold to and could cost it customers.
The money changed after the IPO; the rule did not disappear. In October 2021 Hydrofarm took out a new $125 million senior secured term loan, with JPMorgan Chase Bank acting as administrative agent for the lenders. Its annual report for 2024 described the updated wording: the credit facilities prohibited direct sales of products, inventory or services to cannabis growers operating in any country that prohibits cannabis other than in line with its own laws. Because cannabis remains federally illegal in the United States, that formula kept American growers off the direct customer list.
Ceresnie described the scope the same way. “The former term loan agreement restricted direct sales to licensed commercial cannabis cultivators in the United States,” he told The Cannex. Outside the United States, he said, Hydrofarm already sells directly to commercial customers.
How Hydrofarm Sold Around the Ban
A ban on direct sales did not stop Hydrofarm gear from reaching cannabis grow rooms. It changed the route. According to the 2020 prospectus, the company reached commercial farmers and consumers through more than 2,000 wholesale customer accounts, and more than 80% of its net sales went to specialty hydroponic retailers. The rest went to garden centers, hardware stores, online retailers, greenhouse builders and commercial resellers. Today the network is smaller: Ceresnie said growers bought Hydrofarm products through “approximately 1,000 wholesale accounts, primarily independent hydroponic retailers and commercial resellers.”
In practice, a licensed grower who wanted a pallet of Hydrofarm nutrients bought it from an independent hydroponics store, which bought it from Hydrofarm. The store did not sell exclusively to cannabis, so the sale passed the lender’s test. Ceresnie summed up the cost of that arrangement: the restriction “added a layer between us and the operators who use our products which created friction in the sales and service process.”
There is an irony here. In the 2020 filing, Hydrofarm’s leadership described large-scale, professional multi-state operators as a second major customer segment emerging alongside retail shops, and the company had built a commercial team and an inventory program to serve such users through its resellers. Ceresnie confirmed that this work never stopped. Hydrofarm’s North American technical sales team, he said, “has always worked with commercial operators to specify and support our products, even though we could not invoice them directly while the restriction was in place.” In other words, a Hydrofarm specialist could help a grower choose the lights and plan the nutrient program, but the order and the invoice had to go through someone else’s store.
How a $109 Million Debt Disappeared
The way the loan ended matters, because no one wrote a $109 million check. According to the November 3 release, before the deal Hydrofarm owed $109 million under the term loan, with about $12 million of debt service a year. In the recapitalization the loan was eliminated, and the former lenders received $27.5 million of a new class of Series 1 non-voting convertible preferred stock, convertible into common shares at $1.00 per share, plus warrants to buy 27.5 million common shares at $0.78 each. Separately, Hydrofarm sold common stock and warrants to investors, raising about $8.3 million before costs, with officers and directors taking part on the same terms. After the offering and the conversion of the preferred stock, the company expects to have about 41.8 million common shares outstanding.
An everyday analogy: imagine a homeowner who cannot keep up with mortgage payments, and a lender who agrees to tear up the mortgage in exchange for a share of the house. The monthly payments vanish, the house is no longer pledged, and the lender’s special conditions go with the mortgage, but the lender is now a part-owner, and the other owners hold a smaller slice.
The deal still has loose ends. The conversion of the preferred stock and the exercise of the lender warrants require shareholder approval, and Hydrofarm says it will call a meeting for that. The company believes it has regained compliance with the Nasdaq rule requiring at least $2.5 million in stockholders’ equity, but it remains out of compliance with the rule requiring a minimum share price of $1, and it notes there is no assurance Nasdaq will agree on either point. A small amount of other debt, a foreign subsidiary’s credit line and mortgage, also remains.
Cannabis Banking Beyond Dispensaries: Suppliers Get Caught Too
Hydrofarm’s story is not a one-off. In August 2026 the Government Accountability Office, the investigative arm of Congress, published a report titled Banking Services: Cannabis Businesses Face Access Challenges. Its definition of a cannabis-related business explicitly covers both plant-touching companies and ancillary ones, naming suppliers of growing equipment as an example.
GAO found that the number of financial institutions reporting services to cannabis-related businesses grew from 2015 to 2019 and then stayed relatively flat through 2024. About 1,000 banks and credit unions filed the special suspicious activity reports in 2024. GAO cautions that this figure does not show how many institutions accept cannabis businesses as ongoing customers: some report a one-off transaction, some may not realize a customer is cannabis-related, and some serve only ancillary businesses. Institutions told GAO that the possibility of legal and regulatory sanctions and the cost of compliance were the main reasons to stay away, while others serve the sector to meet community needs or as a business opportunity.
Business owners described the other side of the counter: accounts closed without warning, high account fees, and high interest rates on business loans. They also said that accepting customer payments is difficult, largely because two major credit card companies prohibit cannabis purchases. That is the main reason so many shops still run on cash.
We asked Hydrofarm which financial barriers other than lenders, such as banking, payments or insurance, still affect suppliers like it. The company answered our other questions but left that one unanswered.
The report’s evidence is mostly qualitative. GAO held focus groups and interviews with 74 financial institutions and eight focus groups with owners and managers from 51 cannabis-related businesses, chosen to cover different sizes and types rather than to form a statistical sample. It shows the range of experiences well, but it cannot say how common each problem is nationwide. What Hydrofarm adds is a mechanism the report touches only indirectly: even when a lender never handles a single dollar from a cannabis sale, it can push the industry’s risk onto a borrower’s sales policy, and that policy then shapes who growers can buy from.
Does Schedule III Fix Cannabis Banking?
Many people assumed that rescheduling would end the banking problem. So far it has not. A final rule published on April 28, 2026 moved two categories from Schedule I to Schedule III: FDA-approved marijuana products and marijuana regulated under a state medical marijuana license. Recreational marijuana, even where a state allows it, stayed in Schedule I. For medical licensees the biggest immediate gain is tax relief, because the Section 280E ban on ordinary business deductions applies only to Schedule I and II substances.
Schedule III still means a controlled substance. Businesses handling it need a DEA registration, a process we covered in detail in our report on DEA registration forms for medical marijuana businesses. Law firm Holland & Knight noted in its analysis of the April order that the change should not fundamentally alter the existing banking framework, because suspicious activity reporting still applies. The broader question of moving all marijuana to Schedule III is stuck: on September 29 the DEA’s chief administrative law judge paused the hearing while he decides whether to admit a new GAO report on drug scheduling into the record.
For a lender, the picture remains a patchwork. A medical grower in one state may now operate under Schedule III with a DEA registration, while an adult-use grower across the state line handles a Schedule I substance. As our state-by-state guide to cannabis laws shows, many companies hold both kinds of licenses at once.
The SAFE Banking Act: Back in Congress, Still Not Law
The fix the industry has wanted for years is a law that tells federal banking regulators to leave institutions alone when they serve state-legal cannabis businesses. The latest version, the SAFE Banking Act of 2026, was introduced in the Senate on June 24, 2026 by Sen. Jeff Merkley of Oregon and referred to the Senate Banking Committee. A House companion bill, H.R. 9471, followed on June 25, led by Rep. David Joyce of Ohio.
The bill’s own description is worth reading closely: it would protect financial institutions that provide services to state-sanctioned marijuana businesses and to service providers for such businesses. That second group covers companies like Hydrofarm. If it became law, a lender could still impose its own conditions, but it would lose much of the regulatory reason to forbid sales to licensed growers.
History counsels patience. Earlier versions of the bill passed the House seven times without ever becoming law, because the Senate never held a final vote. GovTrack, a nonpartisan legislative tracker, gives the Senate bill a 7% chance of enactment and the House bill 8%, based on statistical models rather than political reporting.
What Hydrofarm’s Direct Sales to Growers Will Look Like
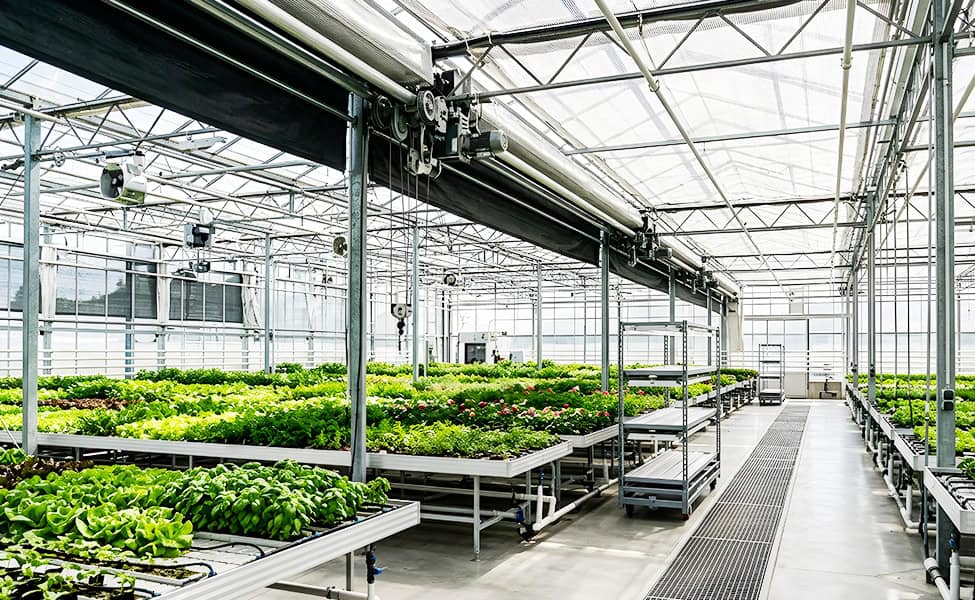
For licensed growers, the direct effect is modest but real: one more large supplier can now open accounts with them, quote volume prices and ship without a middleman. Commercial grow rooms are complex, tightly controlled environments, as an Oklahoma study of more than 113,000 sensor readings showed, and large operators tend to value technical support from the companies that make their equipment.
Hydrofarm presents the new channel as an extension of work already under way. “We have been building this channel for many years,” Ceresnie said, adding that “the commercial cannabis end-market is already about a 1/3 of our business.” That figure should not be set against the 2020 prospectus as a trend: the earlier estimate spoke of cannabis industry participants as the ultimate buyers of a majority of the company’s equipment and supplies, the new one of the commercial cannabis end-market as a share of the business, and the two statements are six years apart.
The company is now opening direct accounts with commercial cultivators. According to Ceresnie, those customers get dedicated account managers and direct shipments from Hydrofarm’s distribution centers, along with “a higher level of service, technical support, and supply consistency.” The brands he expects to lead the commercial channel are Innovative Growers Equipment (IGE) rolling benches and multi-tier racking, the House & Garden, Grotek and Heavy 16 plant nutrition programs, Gaia Green organic fertilizer, Roots Organics soils, coco coir growing media and PhotoBio horticultural lighting. There is a twist in the first name on that list. According to Hydrofarm’s annual report for 2021, the company used proceeds of its 2021 term loan to fund the cash portion of the IGE acquisition. The loan that helped buy the bench maker came with the clause that kept those benches from being invoiced directly to American cannabis growers.
IGE has since changed shape, but not owner. According to Hydrofarm’s second-quarter 2024 results, the company completed a sale of assets related to the production of IGE equipment in May 2024, for gross proceeds of $8.7 million, and entered into an exclusive supply agreement under which the buyer provides contract manufacturing. “We own Innovative Growers Equipment,” Ceresnie told The Cannex. “The 2024 transaction was only for the manufacturing facility and inventory – the buyer in that transaction is now a supplier to us.” Put simply, Hydrofarm kept the brand and the customers and handed the factory work to a contractor.
The obvious question is what happens to the hydroponic stores that carried Hydrofarm products while the ban lasted. Ceresnie said independent retailers “have been central to our business for decades, and they remain so.” The direct channel, in his words, “is aimed at large scale cultivators who buy in volume and need technical support and supply consistency at a scale that is difficult to serve through retail,” and the company sees it “as reaching customers who are not buying through retail today, rather than taking business from partners who serve a different kind of grower.” Whether store owners see it the same way will become clear only once direct accounts start to grow.
For the next six to twelve months, Ceresnie said growers can expect “a higher level of technical service and product support, more direct engagement with commercial cultivators and end users of every size, short-lead times and supply consistency, along with continued new product development across our proprietary brands.”
Outside the United States: Direct Sales Were Already Allowed
The lender’s clause was aimed at countries where cannabis is illegal under national law, so it bit hardest in the United States. Abroad, Ceresnie said, Hydrofarm already sells directly to commercial customers, and the pharmaceutical-grade medical cannabis sector “is a key focus for us there.” The company says it has sales in more than 30 countries and serves Europe from a full-service distribution center in Zaragoza, Spain, which it already listed among its sites at the time of the IPO. According to Ceresnie, House & Garden and Grotek are leading brands in markets including the UK, Spain, Australia, Israel, Thailand and Argentina, and the company is expanding in Eastern Europe, Africa, South America and Asia.
Germany, where adults may grow cannabis at home or through non-profit cannabis social clubs, gets particular attention. “Germany is a strategic market for us,” Ceresnie said. Several Hydrofarm nutrient and lighting brands are sold there through distributors and retailers, larger commercial accounts are served directly from Zaragoza, and the company says it is “particularly focused on supporting Germany’s cannabis social clubs, which we believe are a strong and growing segment of the market.” Home growers are served through the retail and distributor network, and medical cannabis producers both directly and through distributors.
For club organizers, the practical question is whether they have to go through a distributor. In follow-up answers, Ceresnie said they do not: “Yes, social clubs can open direct accounts.” There is no single entry threshold, he added: “Minimum orders vary depending on product categories.” The company did not give specific minimums. These are the company’s own descriptions of its market position; we have not seen independent sales data for Germany.
What Hydrofarm Still Has to Prove
Everything in the previous two sections describes plans. The November 3 release lists direct commercial sales as one of several growth priorities, alongside organic brands, international expansion, e-commerce and logistics services, and frames them as forward-looking statements. Neither the release nor Ceresnie’s answers give figures for expected direct cannabis sales. The company’s own risk list includes a history of operating losses, possible dilution for existing shareholders, the pending shareholder vote and Nasdaq listing requirements.
None of this changes the banking position of the growers themselves. Their access to accounts, card payments and loans still depends on federal law, which affects how licensed businesses compete with the illicit market on price, a theme that also runs through Missouri’s data on regulated cannabis spending. Hydrofarm got out from under its restriction by retiring the loan that imposed it. Most of the industry has no such exit until Congress or federal regulators change the rules.
FAQ
Many are not entirely cash only today, but cash remains common because card payments are hard to arrange. According to the Government Accountability Office, two major credit card companies prohibit cannabis purchases, and many banks avoid or limit accounts for cannabis businesses because of federal law. Shops that do accept cards often rely on debit-based workarounds rather than standard card processing.
Generally not in the usual way. Because the major card networks prohibit cannabis purchases, most dispensaries cannot run a standard credit card sale. Some offer debit options, cashless ATM transactions or in-store ATMs, and the rules and fees vary by state and payment provider.
There is no official public list, and the answer changes often. Federal data show that about 1,000 banks and credit unions filed cannabis-related suspicious activity reports in 2024, many of them community banks and credit unions. Filing such a report does not always mean the institution keeps cannabis businesses as long-term customers, so businesses usually ask a bank directly about its policy.
No federal law specifically forbids it, but federal law still makes most marijuana illegal, so banks that serve cannabis businesses take on legal and regulatory risk. Federal guidance from 2014 explains how banks can serve marijuana-related businesses if they carry out detailed due diligence and file suspicious activity reports. Only state-licensed medical marijuana and FDA-approved products have moved to Schedule III; recreational marijuana remains in Schedule I, and the SAFE Banking Act, which would create explicit protection, has not been passed. Specific situations should be reviewed by a qualified attorney.
Legal Disclaimer
This article is for general information and news purposes only and does not constitute legal, financial, tax or investment advice. It does not recommend buying or selling any security, including shares of Hydrofarm Holdings Group. Cannabis remains a controlled substance under United States federal law, and federal and state rules on cannabis, banking and lending differ and change frequently. Company statements described here, including the written comments Hydrofarm provided to The Cannex, reflect the company’s own views and include forward-looking statements that may not come true. Readers should consult a qualified attorney, financial adviser or other licensed professional before making any decision. The Cannex does not encourage the purchase, cultivation or use of cannabis where it is prohibited by law.